
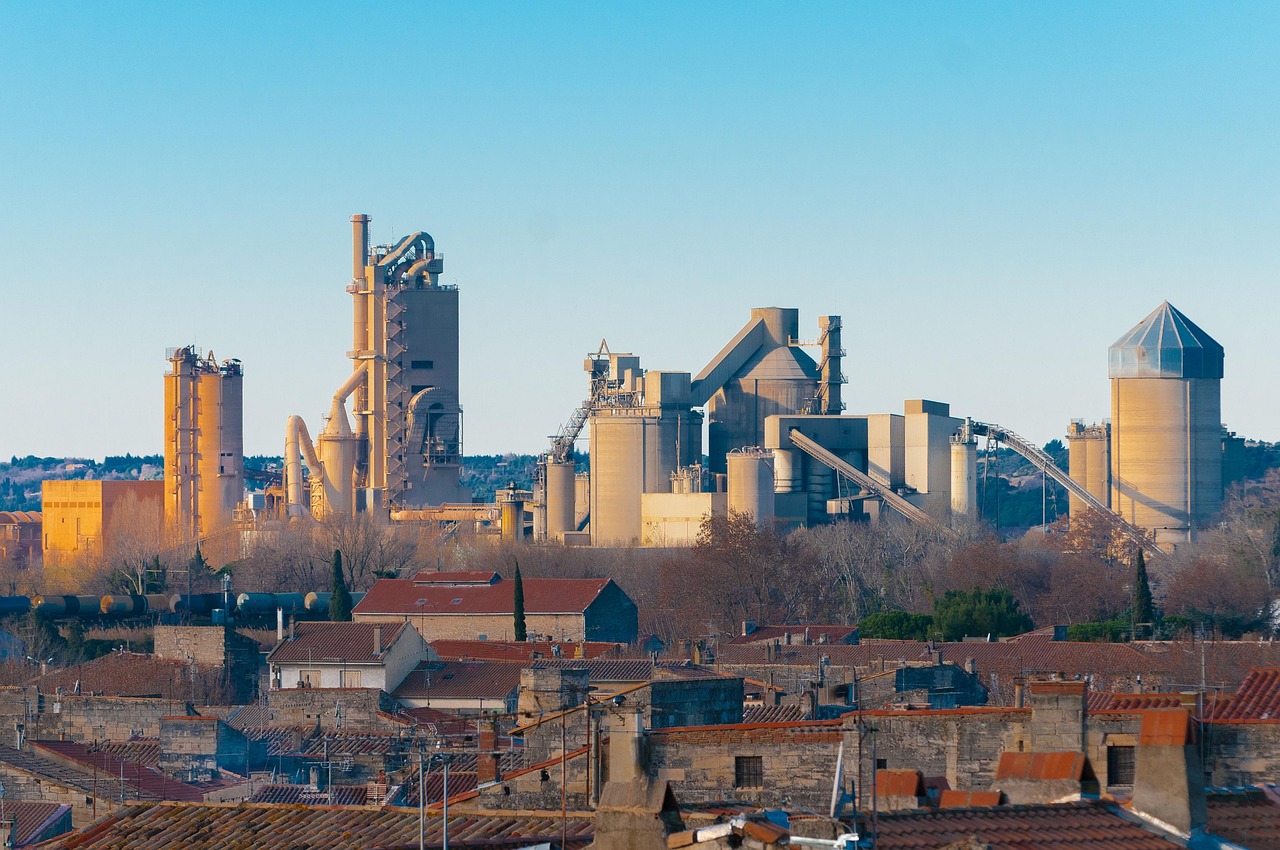
The Ambuja Cements Q2 results look brutal at first glance. Consolidated net profit fell 90% year-on-year to ₹236 crore for the September quarter, against ₹2,336 crore a year earlier, Business Standard reported on Thursday, citing the Adani Group company’s earnings release. But that comparison is lopsided. Last year’s profit carried a ₹1,697 crore reversal of an income-tax provision, a one-time boost that won’t repeat.
So the more useful question is what happened to the operating business. And there, the story is still weak, just not 90% weak.
In this article
Ambuja Cements Q2 results in numbers
- Revenue from operations was ₹9,197 crore, up 0.2% from a year ago.
- Operating EBITDA fell 27.9% to ₹1,271 crore.
- EBITDA margin shrank to 13.8% from 19.2%.
- Cement sales volume slipped 0.6% to 16.5 million tonnes.
- EBITDA per tonne dropped to ₹770 from ₹1,061.
Flat sales and a 28% fall in operating profit tell you costs did the damage. ET Markets reported that total expenses rose over 6% to ₹8,877 crore, with power and fuel costs up nearly 12% at ₹2,552 crore.
Where the cost pressure came from
The company blamed higher petcoke and coal prices, tight coal availability, and costlier diesel and packaging. It also pointed to geopolitical uncertainty and monsoon-related headwinds, on top of the usual seasonal weakness.
Total cost came to ₹4,410 per tonne. Ambuja said that figure would have been ₹4,182 excluding the impact of geopolitical conflicts, and it repeated its target of bringing costs down to ₹4,250 per tonne by the end of FY27. That’s a tall order from here, and we’d want to see the next two quarters before taking it at face value.
The parts that held up
Not everything went the wrong way. Trade volumes, meaning cement sold through dealers and retailers, rose 8.6% and made up 74% of total volumes. Premium products rose to 37% of trade sales from 35%. Green power climbed to 61% of the mix from 41%, and net power cost fell to ₹4.8 per kWh from ₹6.
Capacity kept growing too. Ambuja commissioned 4.6 million tonnes per annum (MTPA) at Dahej, Salai Banwa and Kalamboli during the quarter, and expects 2.4 MTPA at Warisaliganj in the second half of FY27. The board also approved buying a 26% stake in SWE Renewables for ₹33.75 crore to source captive wind power.
What it means for investors
CEO Vinod Bahety said volumes should grow ahead of the industry in the second half. The company also noted that the industry recently raised prices by ₹10-15 per bag. Whether those hikes stick, and whether fuel costs cool, will decide how fast margins recover. Shareholders have also approved merging ACC and Orient Cement into Ambuja, subject to NCLT and regulatory approvals.
It has been a busy results day. Coal India’s Q2 numbers came out the same evening, and sister company Adani Ports raised its FY27 guidance a day earlier. For Ambuja, the cost line is the one to watch.
Disclaimer: This article is for information and education only and is not investment advice. Please do your own research or consult a SEBI-registered adviser before making any investment decision.

Leave a Reply
Join the conversation
Commenting is open to registered readers. Sign up with just your email — no password needed, and it takes under a minute.
Sign up to comment Log in