



Watch a new trader on an expiry morning and you’ll see a lot of activity. Five windows open, an option chain refreshing every second, a finger hovering over the buy button, a stop loss moved three times before 10 am. It looks like control. Often it isn’t. The illusion of control in trading is the belief that because we’re busy, informed and making choices, we have more say over the outcome than we really do. On a random tick, more screen time doesn’t buy you more edge. It just buys you more trades.
This piece looks at where the idea comes from, a study that tested it on professional traders, why Indian F&O screens are close to an ideal breeding ground for it, and a few practical checks that separate the parts of a trade you control from the parts you only feel you control.
In this article
- Where the illusion of control in trading comes from
- What the experiments actually showed
- The trader study: a screen, three keys and a random line
- Why the F&O screen is the perfect setting for it
- Worked example: two traders, the same market
- What you actually control, and what you don’t
- Practical checks to keep the illusion in its place
- Is a sense of control always bad?
Where the illusion of control in trading comes from
The term was coined by the American psychologist Ellen Langer. As the Wikipedia summary of the research puts it, the illusion of control is the tendency for people to overestimate their ability to control events, including outcomes they demonstrably don’t influence. It sits alongside optimism bias and illusory superiority in the group psychologists call positive illusions.
Langer’s explanation was about what she called skill cues. These are features of a situation that we normally associate with games of skill: having a choice, competing against someone, being familiar with the setting, and being personally involved in decisions. Put those cues into a game of pure chance and people start behaving as if skill matters.
Read that list again with a trading terminal in mind. Choice? You pick the strike, the lot size, the entry. Competition? There’s a counterparty on every trade and a leaderboard on every social feed. Familiarity? You’ve watched Nifty every day for two years. Involvement? You clicked the button yourself. A trading screen hands you every skill cue at once, whether or not the next five-minute candle has anything to do with skill.
What the experiments actually showed
A few of the classic findings are worth knowing, because they map onto trading habits almost too neatly.
- The coin-toss study. Subjects predicted the outcome of thirty coin tosses, and the feedback was rigged so everyone was right exactly half the time. The only difference was when the hits came. People who got their correct guesses early overestimated their total successes and expected to do better in future rounds. Forty percent of subjects believed their performance on this pure-chance task would improve with practice, and twenty-five percent said distraction would hurt it.
- The lottery ticket. People who chose their own lottery ticket were more reluctant to swap it for another, even when offered a ticket with better odds, than people who were handed one at random.
- The dice. In craps, players tend to throw harder when they need high numbers and softer when they need low ones.
The research summary also notes that the illusion is stronger in familiar situations, stronger when feedback emphasises success rather than failure, and strengthened by stressful and competitive settings, with financial trading named as one of them.
If you’ve ever had three winning trades on a Monday and felt like you’d “figured out” the market for the week, that’s the coin-toss result in your own P&L. The early hits didn’t change the odds. They changed how you felt about the odds.
Early wins don’t change the odds of the next trade. They only change how confident we feel about it, and confidence is not a position-sizing input.
The trader study: a screen, three keys and a random line
The most direct test on market professionals is a 2003 study by Fenton-O’Creevy, Nicholson, Soane and Willman, published in the Journal of Occupational and Organizational Psychology under the title “Trading on illusions”. The researchers worked with traders at investment banks in the City of London.
Each trader watched a line being plotted on a screen, much like a live price chart, and was given three keys to try to push the value as high as possible. They were told the line moved randomly but that the keys might have some effect. In reality the keys did nothing at all. How much success the traders believed they’d had became the measure of how prone each one was to the illusion.
Then came the useful part. Those scores were compared with how the traders actually performed at work. The ones more prone to the illusion were rated significantly lower on analysis, risk management and contribution to profits, and they earned significantly less.
The same authors argue that while a sense of control can keep people striving towards goals, it works against sound decision-making. Illusions of control can make people less sensitive to feedback, slow down learning and push them towards taking more objective risk, because the risk feels smaller when you believe you’re steering.
That last point is the expensive one. A trader who thinks he controls the outcome sizes up. A trader who knows he doesn’t, sizes down.
Why the F&O screen is the perfect setting for it
SEBI itself points to the increased participation of individual investors in equity derivatives, and its own numbers show how that has gone for most of them. In its September 2024 press release on its F&O study, SEBI said 93% of over 1 crore individual equity F&O traders made losses over FY22 to FY24, with an average loss of around ₹2 lakh per trader including transaction costs. Aggregate losses of individual traders over those three years exceeded ₹1.8 lakh crore.
Two other lines from that release are worth sitting with. First, 97% of FPI profits and 96% of proprietary trader profits in FY24 came from algorithmic trading, which tells you the side that wins is largely the side that has taken the human finger off the button. Second, more than 75% of loss-making individual traders kept trading F&O despite consecutive years of losses.
We can’t say from that data how much of the loss is down to any single bias, and we won’t pretend otherwise. But the pattern fits the illusion of control uncomfortably well: lots of choice, lots of involvement, lots of familiarity, and a belief strong enough to survive years of contrary results.
Worked example: two traders, the same market
Here’s a hypothetical illustration. The numbers are made up to show the mechanics; they aren’t drawn from any real account or index level.
Trader A has ₹5,00,000 in capital. She trades one plan: a defined setup, a stop of ₹2,000 per trade, a target of ₹3,000, and a cap of three trades a day. Let’s say her setup wins 40% of the time. Over 50 trades, she expects roughly 20 winners and 30 losers:
- 20 winners × ₹3,000 = ₹60,000
- 30 losers × ₹2,000 = ₹60,000
- Net before costs: ₹0
Break-even before costs. Not exciting, but honest, and it tells her the setup needs work, not more activity.
Trader B has the same capital and, on paper, the same setup. But after a few early winners he feels he’s “reading” the market. He adds discretionary trades whenever he senses a move, nudges stops wider when a trade goes against him because he’s “sure” it will come back, and doubles his size after wins. Over the same stretch he takes 150 trades instead of 50.
Suppose his extra 100 trades are pure noise, winning half the time with symmetric ₹2,000 wins and losses. Before costs they net to zero. Now add costs. If each round trip costs him ₹100 in brokerage, exchange charges and taxes (again, a hypothetical figure for the sake of arithmetic), those 100 extra trades cost ₹10,000 that Trader A never paid. And that’s the kind version. Widening stops on losers means his average loss grows while his average win doesn’t, which is how break-even setups quietly turn into losing ones.
Nothing Trader B did changed the probability of the next candle. All he changed was how often he paid to find out.
What you actually control, and what you don’t
It helps to write this down once and keep it near the screen.
| You control | You don’t control |
|---|---|
| Which setups you trade | Whether the next trade wins |
| Position size and maximum loss per trade | Gap openings and overnight news |
| Where the stop sits before you enter | How fast price moves through your stop |
| How many trades you take in a day | Which way the index closes |
| When you switch off the terminal | What FIIs, algos or other traders do next |
Everything in the left column is a decision made before or outside the trade. Everything in the right column is the market. The illusion creeps in when we start treating right-column items as if they were left-column ones: “I’ll hold, it’ll bounce”, “I can feel the reversal coming”, “one more lot, this one’s a sure thing”.
Put your effort into the decisions you make before the order goes in. Once it’s live, the market has the wheel.
Practical checks to keep the illusion in its place
1. Keep a trade log that records the reason, not just the result
The coin-toss study shows how memory flatters early wins. A written log fixes that. For every trade, note the setup, the planned stop and target, and whether you followed the plan. At month-end, look at plan-followed trades and off-plan trades separately. That split tells you whether the losses come from the setup or from you.
2. Decide size before you look at the live chart
The Fenton-O’Creevy point about risk is that illusory control makes risk feel smaller. So take the feeling out of sizing. Fix a maximum loss per trade as a share of capital and calculate the quantity from your stop distance, every single time, before the chart has a chance to talk you into anything.
3. Cap the number of trades
A daily limit sounds crude, but it directly attacks the “more activity, more control” belief. When you only have three bullets, you stop firing at noise.
4. Separate process grades from P&L grades
Score each trade twice: did I follow the plan, and did it make money? A well-executed trade that lost is a good trade. A random punt that happened to win is a bad one. If you only score the second column, luck will keep teaching you the wrong lessons.
5. Test the “edge” before you trust it
If you believe you can read intraday moves, write the rule down and backtest or paper-trade it over a meaningful sample. If the rule can’t be written down, that’s usually a sign the edge lives in your head rather than in the data.
6. Watch for skill cues on a bad day
The research suggests stress and competition make the illusion stronger. So on days when you’re down, rattled or comparing your P&L with someone else’s screenshots, assume your sense of control is inflated and cut size or stop for the day.
Is a sense of control always bad?
No. Some psychologists argue that positive illusions help people persist at hard tasks, and a trader who believed he had no influence over anything wouldn’t build a process at all. The trouble is narrower: overestimating control over outcomes that are mostly chance. The psychologist Albert Bandura made the relevant distinction in 1997, arguing that in activities where margins of error are narrow and missteps are costly, well-being is best served by highly accurate self-assessment. Leveraged trading is about as narrow-margin as everyday life gets.
So keep the confidence for the things that deserve it: your preparation, your rules, your sizing and your discipline in following them. For the rest, accept that a single trade is closer to a coin toss than most of us like to admit. If you want to go deeper on the habits that sit next to this bias, our pieces on action bias in trading and confirmation bias in trading cover the urge to act and the urge to see only what agrees with us. For the money side, sizing, stops and drawdown limits, start with our guide to risk management in trading.
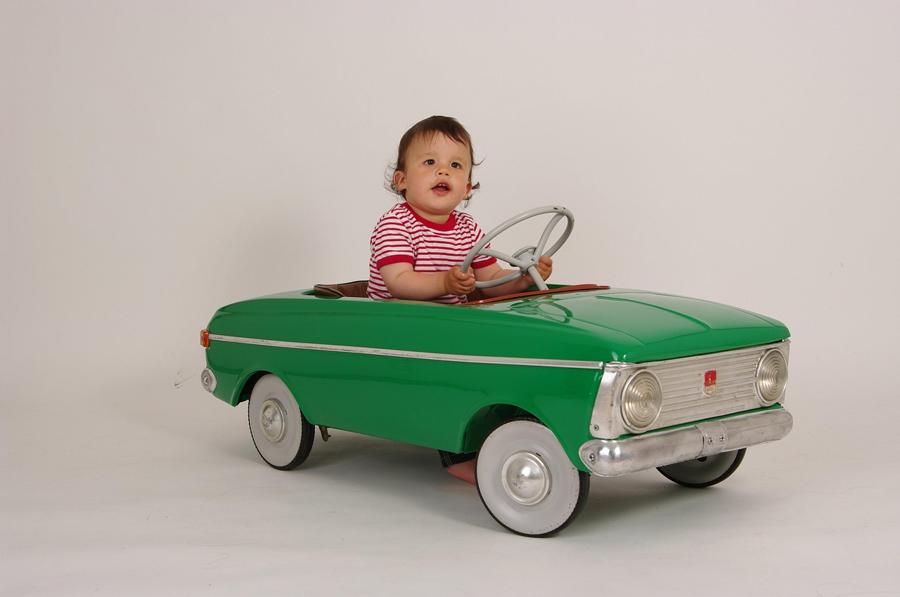
The pedal car has a steering wheel, and the child turning it is having a great time. It just isn’t connected to the wheels. A lot of trading activity works the same way. The skill is knowing which parts of your setup are wired to the outcome, and leaving the rest alone.
Disclaimer: This article is for educational purposes only and is not investment advice. Trading in equities and derivatives involves risk of loss. Please consult a SEBI-registered investment adviser before making investment decisions.

Leave a Reply
Join the conversation
Commenting is open to registered readers. Sign up with just your email — no password needed, and it takes under a minute.
Sign up to comment Log in