
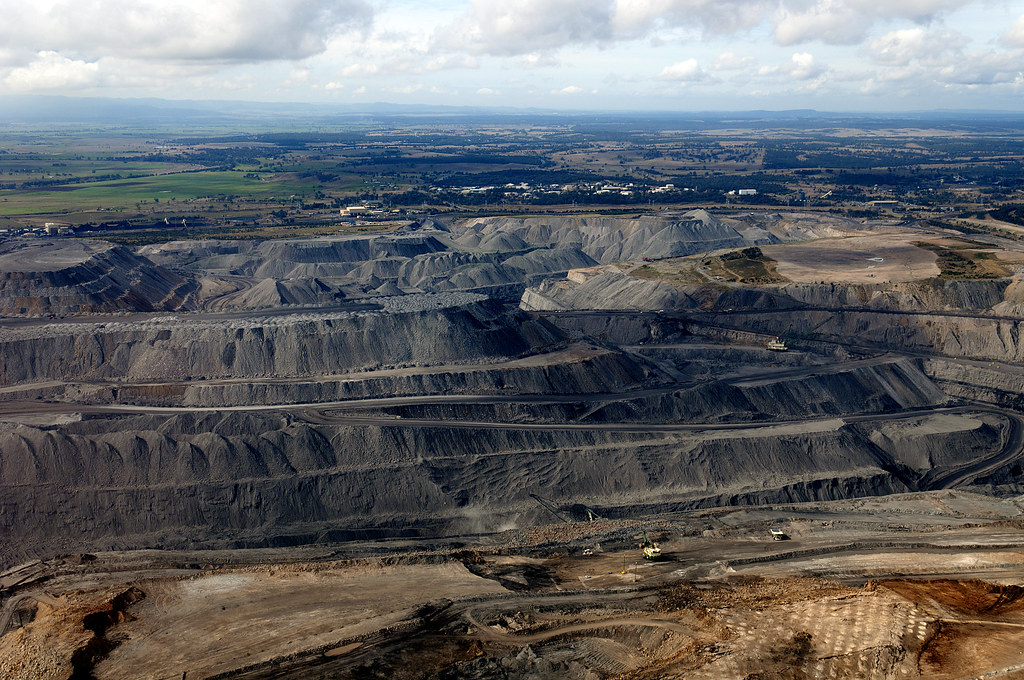



Bharat Coking Coal picked a Sunday to report, and the headline looks clean. The BCCL Q2 results show a standalone net profit of ₹123.74 crore for July-September 2026, against a loss of ₹52.99 crore in the same quarter last year, according to the results presentation the Coal India subsidiary filed with BSE and NSE on October 25, 2026. Look one layer down, though, and a single income line explains most of the swing.
In this article
BCCL Q2 results: the key numbers
All figures below are standalone, for Q2 FY27 against Q2 FY26, taken from the company’s presentation:
- Revenue from operations: ₹4,412.58 crore, up from ₹3,173.25 crore. That is a 39.06% year-on-year rise.
- Total income: ₹4,571.15 crore versus ₹3,643.54 crore, up 25.46% year-on-year.
- Profit before tax: ₹185.78 crore, against a pre-tax loss of ₹48.06 crore.
- EBITDA: ₹358.87 crore, up from ₹86.65 crore.
- Raw coal production: 7.22 million tonnes against 6.71 million tonnes, a 7.6% year-on-year increase, but short of the quarter’s 7.69 million tonne target.
- Offtake: 8.89 million tonnes against 8.11 million tonnes, up 9.6% year-on-year and ahead of the 8.28 million tonne target.
Basic EPS came in at ₹0.27, compared with a loss of ₹0.11 per share a year ago, as ETEnergyWorld reported.
The ₹386.5 crore line
BCCL’s own variance table says revenue grew for three reasons: outside dispatch went up from 8.03 to 8.93 million tonnes, the average price of washed coal rose from ₹9,437 to ₹12,681 a tonne, and the company booked ₹386.50 crore of performance incentive and compensation income, against nil in the same quarter last year.
That last item is the one we would watch. On simple arithmetic, take ₹386.5 crore out of the ₹185.78 crore pre-tax profit and the quarter flips to a pre-tax loss of roughly ₹200 crore. The incentive is real income, but it is not the same as mining coal more cheaply, and investors will want to know how much of it repeats.
Costs also climbed. Total expenses rose 18.79% to ₹4,385.37 crore. Other expenses jumped 30.70% to ₹1,369.82 crore, which the company puts down to a higher JMBL cess (₹450 a tonne against ₹250) and a 40% increase in power tariff. Employee costs rose to ₹1,621.30 crore and include a ₹76.07 crore wage-agreement (NCWA XII) provision. Other income, meanwhile, fell 66.28% to ₹158.57 crore because of lower liability write-backs.
The half-year picture is weaker
Q2 looks better partly because Q1 was poor. For the half year, profit after tax was ₹55.65 crore against ₹123.88 crore a year earlier, which implies a Q1 FY27 loss of about ₹68 crore. Half-year production fell 12.51% to 13.78 million tonnes, well below the 17.22 million tonne target. The company also noted the new 2 million tonne Bhojudih washery started commercial operations in May, taking total washing capacity to 17.35 million tonnes.
What it means for the stock
The shares go into Monday’s session near their lows. BCCL ended Friday, October 23, at ₹29.88, down 1.03%, as Zee Business noted. That is still above the ₹23 IPO price but far from the January listing-day high. Upstox data put the 52-week low at ₹28.92, hit on October 23, and market capitalisation at ₹13,859 crore.
A first-glance read may cheer the turnaround. The better question is whether better washed-coal prices and higher dispatches can carry profits once the incentive income fades. If you are new to reading results this way, our guide on how to analyse quarterly results walks through separating one-off items from operating profit. For background on BCCL’s listing, see our IPO investing guide, and for a basket approach to state-run companies, our explainer on the CPSE ETF.
Disclaimer: This article is for information and education only and is not investment advice. Please do your own research or consult a SEBI-registered adviser before making any investment decision.

Leave a Reply
Join the conversation
Commenting is open to registered readers. Sign up with just your email — no password needed, and it takes under a minute.
Sign up to comment Log in